Moving Out for the First Time: How to Manage Your Household Budget
Moving Out for the First Time: How to Manage Your Household Budget
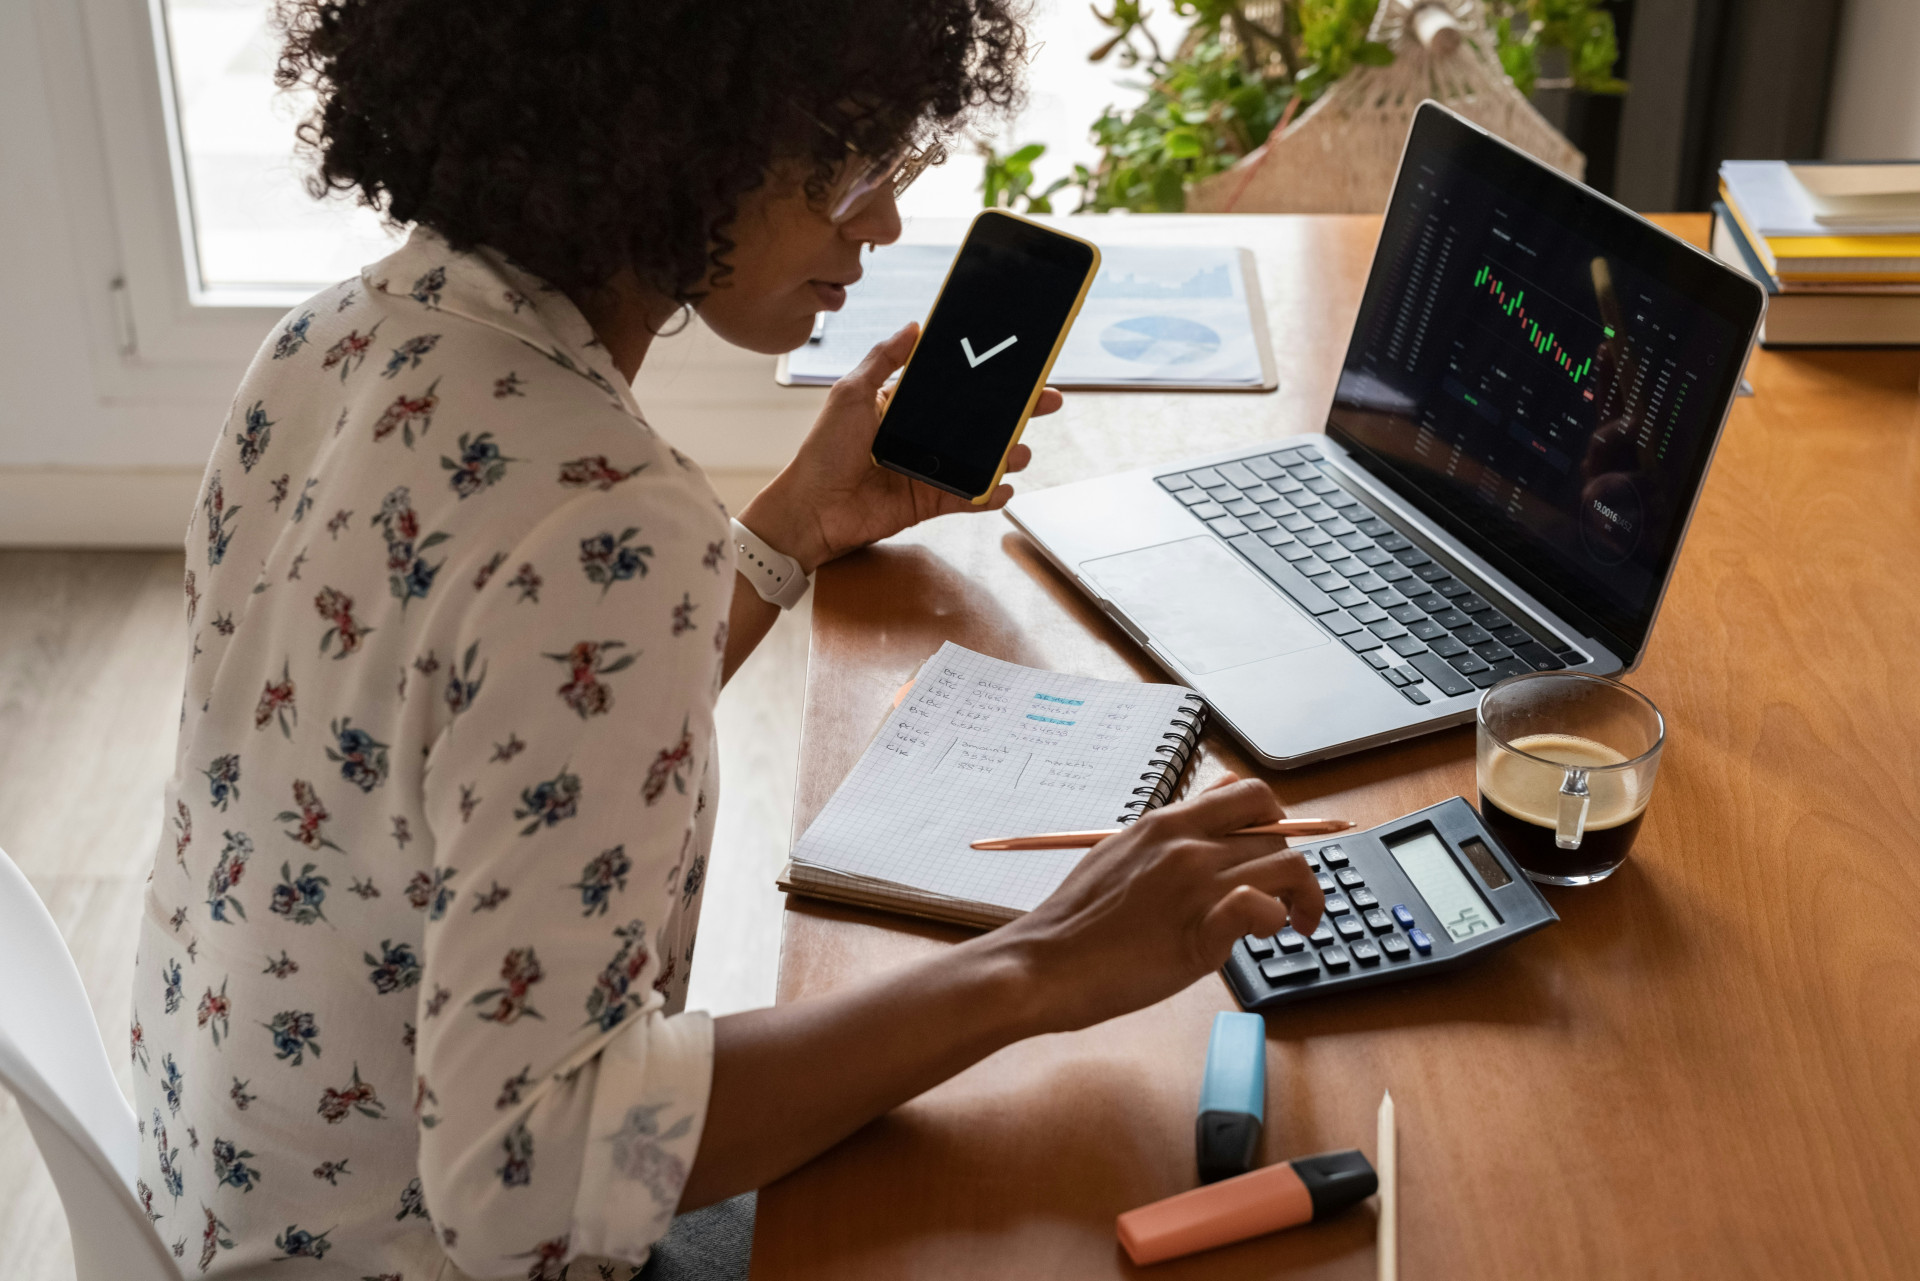
Moving out on your own for the first time is a huge milestone—and one of the most exciting transitions in life. But it’s also the moment when you start taking full responsibility for your own finances. Rent, utilities, groceries, internet, and insurance can add up quickly, and without a plan, it’s easy to lose track of where your money goes. Here’s a guide to help you manage your household budget from day one.
Start with a Realistic Budget
The first step toward financial stability is knowing exactly how much money you have coming in and going out. Create a simple monthly budget that lists all your fixed and variable expenses.
Fixed expenses might include:
- Rent
- Utilities (electricity, water, gas, internet)
- Insurance (renter’s, health, car)
- Transportation (car payment, gas, public transit)
- Subscriptions (streaming services, gym memberships)
Variable expenses are those that change from month to month:
- Groceries
- Dining out and entertainment
- Clothing
- Gifts and personal care
- Unexpected costs
Once you’ve listed everything, you’ll see how much you have left for fun—and where you might be able to cut back. There are plenty of free budgeting apps and templates that can help you stay organized and track your spending automatically.
Læs også:
Understand Your Housing Costs
Rent is usually your biggest monthly expense, but it’s rarely the only one. Many first-time renters forget to factor in utilities, trash collection, or renter’s insurance. Before signing a lease, ask your landlord what’s included in the rent and what you’ll need to pay separately.
When you move in, take photos of meter readings for electricity, gas, and water to avoid disputes later. It’s also smart to look for ways to save on energy—turn off lights when you leave a room, unplug electronics, and use energy-efficient bulbs. Small habits can make a noticeable difference on your utility bills.
Plan Your Food Budget
Groceries and dining out can easily become one of your biggest expenses. It’s tempting to grab takeout after a long day, but those costs add up fast. Plan your meals for the week, make a shopping list, and stick to it. Buying in bulk, cooking at home, and using leftovers can save you a lot of money.
If you live with roommates, consider sharing grocery costs and cooking together. It’s cheaper—and often more fun—than eating out.
Don’t Skip Insurance
Insurance might not be the most exciting part of adult life, but it’s essential. A renter’s insurance policy protects your belongings in case of theft, fire, or water damage, and it’s usually very affordable. You should also make sure you have health insurance, whether through your employer, a parent’s plan, or the Health Insurance Marketplace.
If you own a car, you’ll need auto insurance as well. Shop around for quotes and compare coverage options to find the best deal.
Build Savings and an Emergency Fund
Even if money is tight, try to set aside a little each month. Having a small cushion can make a big difference when unexpected expenses pop up—like a car repair or a medical bill. A good goal is to build an emergency fund equal to one month’s worth of fixed expenses. You don’t have to do it all at once; start small and add to it regularly.
Consider opening a separate savings account so you’re not tempted to dip into your emergency fund for everyday spending.
Avoid Common Pitfalls
It’s normal to make a few mistakes when you’re learning to manage your own finances. Maybe you forget to pay a bill on time or overspend on entertainment. The key is to learn from it and adjust your budget. Avoid taking out payday loans or using credit cards for things you can’t afford to pay off right away—high interest rates can trap you in debt quickly.
If you ever feel overwhelmed, don’t hesitate to ask for help. Many community centers, universities, and nonprofit organizations offer free financial counseling.
Make Money Management a Habit
Managing your household budget isn’t about restricting yourself—it’s about creating stability and freedom. When you know where your money goes, you can plan better and enjoy life without constant stress about bills.
Set aside time once a month to review your budget, check your bank statements, and make any necessary adjustments. It only takes a few minutes but gives you a clear picture of your financial health.
Moving out for the first time marks the beginning of a new chapter. With a little planning and discipline, you can build good financial habits that will serve you for years to come—and enjoy your independence with confidence.
Læs også: